Guides
The startup budget for a locksmith business and the ways to finance it
Locksmith startup costs are best written as named variables you fill from your own quotes, then tested against the ramp period the funding has to cover.
What to take away
What to take away
- The startup budget for a locksmith business is five bucketstooling, vehicle, permission, stock, and working capital for the ramp before the phone is busy.
- A mobile, residential-only shop typically opens on $25,000 to $40,000. Add a new van and automotive programming and the same plan runs $70,000 to $95,000.
- Write every figure as a named variable and fill it from your own quotes. A number copied from an article is an assumption in disguise.
- Finance by asset lifeconsumables from cash, tooling on 2 to 5 year term finance, the van on a term no longer than you keep it.
- SBA Microloans cap at $50,000, SBA 7(a) at $5 million, and Kiva US lends up to $15,000 at 0% interest.
Startup cost articles usually give one range. A single range is useless here. Two locksmith businesses in one city differ by an order of magnitude depending on automotive work, a code machine, and whether the van is new. What travels is the structure of the calculation. Fill the variables below from quotes you received, then date them.
The five buckets
Opening cash requirement = T + V + P + S + W, where:
Opening Cash Requirement Formula
- TTooling
- VVehicle and fit out
- PPermission
- SOpening stock
- WWorking capital for ramp
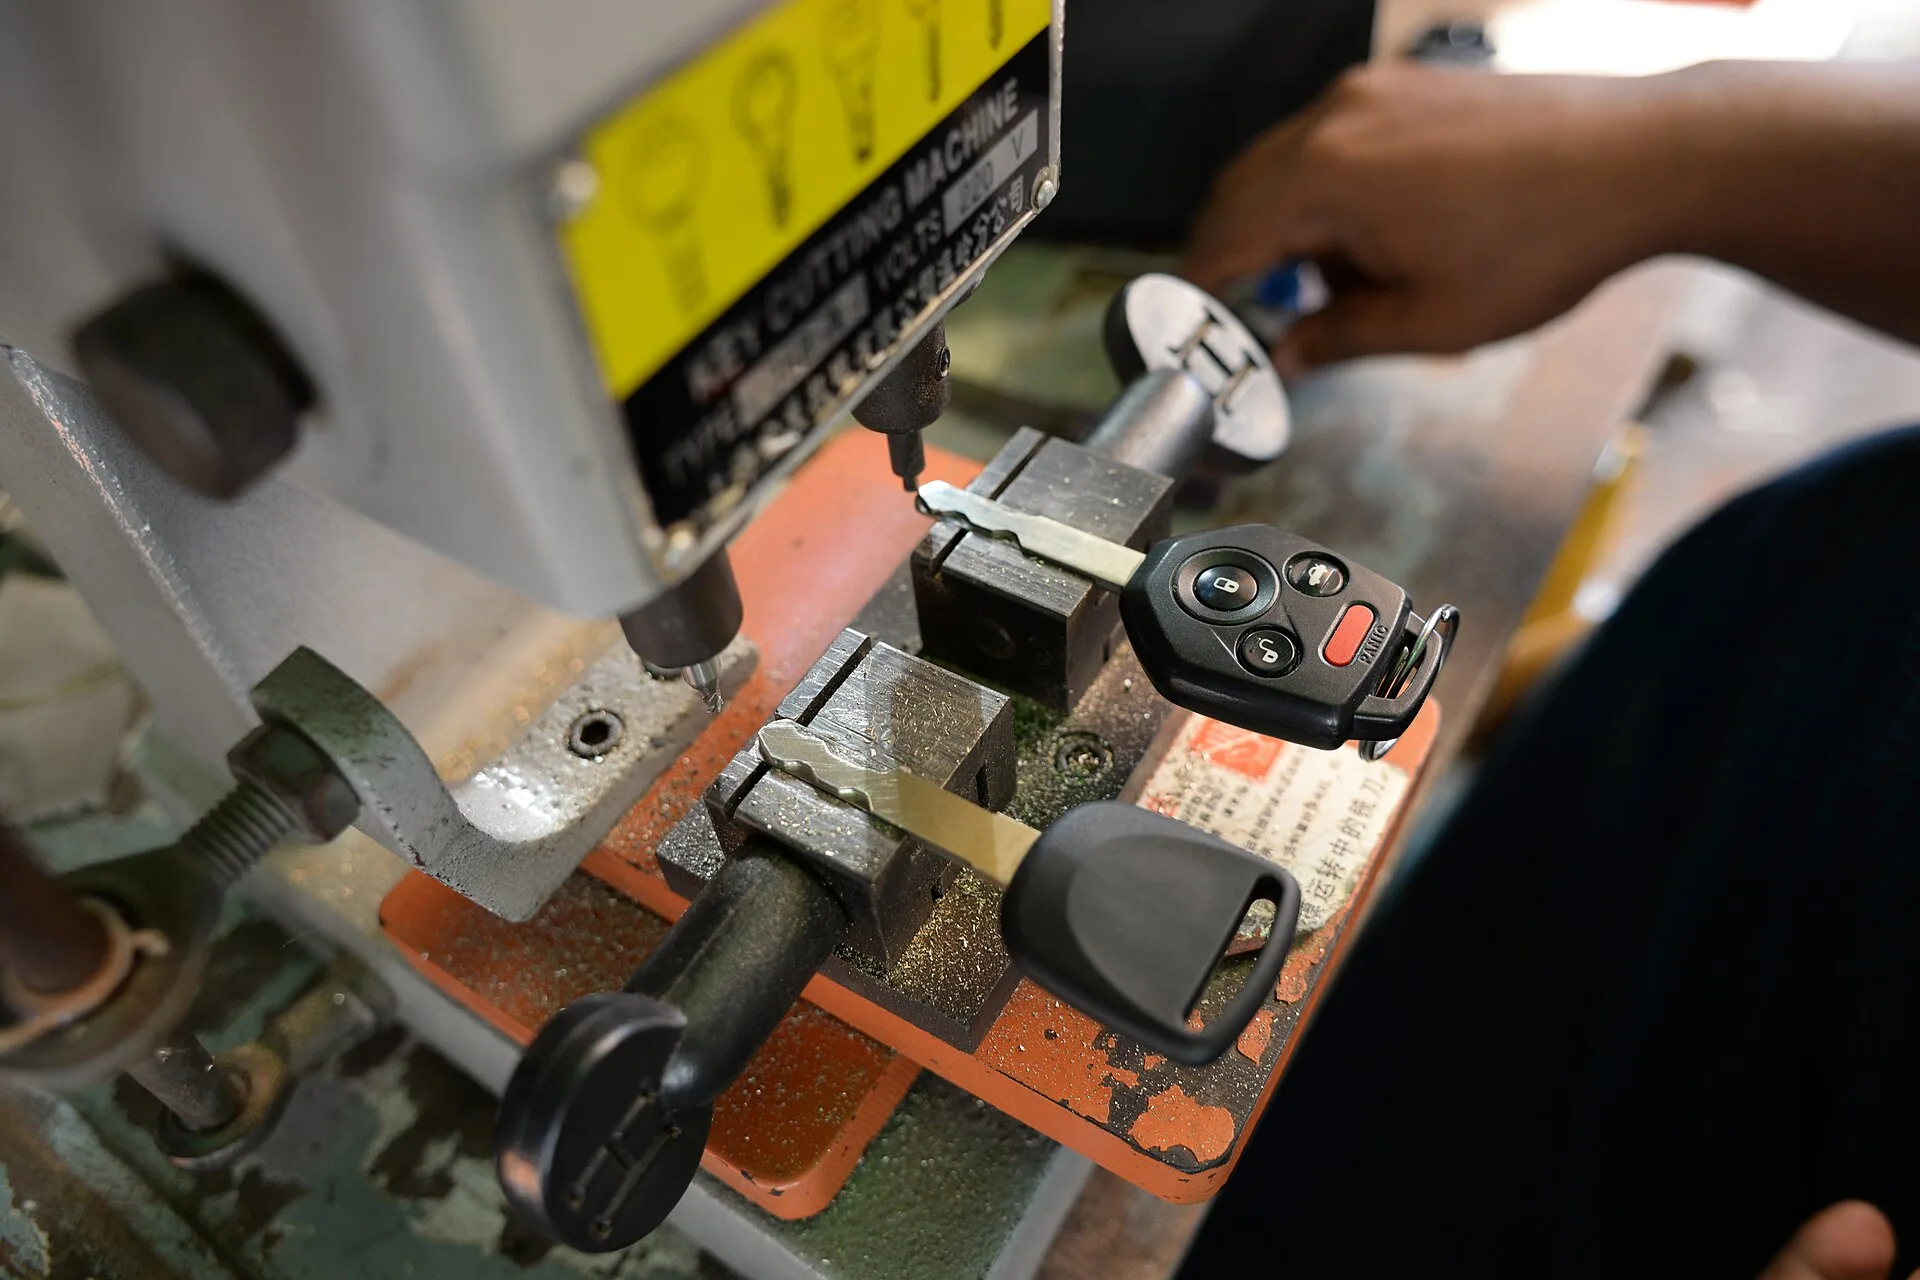
- T is toolingpinning kit and pin stock, duplicator, code machine if the mix needs one, and hand and cordless tools. Add a drill index, key gauges, depth keys, and safe tooling if that work is in scope.
- V is vehicle and fit outthe vehicle, shelving, a bench or vice mount, and power. Add lighting, load security, and signage.
- P is permissionentity registration, any state or city license fee, a bond if required, and insurance deposits. Add the time spent obtaining each.
- S is opening stockkey blanks by keyway, cylinders by function and finish, and deadbolts. Add latches and strikes, closers if commercial work is in scope, and consumables.
- W is working capital for the rampfixed burden multiplied by the months before revenue covers it.
W is the bucket people leave out, and it decides whether the business survives a slow first quarter.
Here are the named items and the typical opening figure each one carries:
The five buckets
| Bucket | Named items | Typical opening figure |
|---|---|---|
| T, tooling | Ilco or Rytan duplicator, LAB or Ilco pinning kit, cordless drill, hand tools, key gauges | $400 to $1,500 for rekey and residential work |
| T, automotive add-on | Autel-class programming tool and its annual software subscriptions | $1,000 to $3,500 for the tool, plus $500 to $1,500 a year |
| V, vehicle | Used Ford Transit Connect or Nissan NV200, new Ford Transit or Mercedes Sprinter | $12,000 to $25,000 used, $38,000 to $55,000 new |
| V, fit out | Shelving, vice and bench mount, power, lighting, load security, signage | $1,500 to $6,000 |
| P, permission | LLC filing, city business license, $10,000 surety bond, liability cover, commercial auto cover | $50 to $500 filing, $50 to $400 license, $100 to $250 bond, $1,700 to $4,000 a year in cover |
| S, opening stock | Key blanks in the keyways you meet, cylinders, deadbolts, latches, strikes | $0.10 to $0.50 a blank in bulk, $800 to $3,000 for hardware |
| W, working capital | Insurance, van finance, phone and software, rent, base draw | $3,750 to $4,550 a month, so $11,000 to $27,000 over a 3 to 6 month ramp |
The low case lands in the high twenties: a used van, basic hand tooling, a small stock buy, and three months of thin fixed burden. The high case tops $90,000 once a new van, automotive programming, and six months of cover are in the plan.
Getting W right
Ramp working capital = monthly fixed burden x expected ramp months.
Ramp Working Capital Calculation
- Monthly fixed burdeninsurance + vehicle finance + phone/software + rent + base wages + minimum drawings
- Expected ramp monthsjudgment, write down what would prove it wrong
A workable starting set of numbers: $150 a month for liability cover, $450 for van finance, $150 for phone and software, $0 to $800 for rent, and a $3,000 draw. That totals $3,750 to $4,550 a month.
A $15,000 van loan at 9% over 60 months costs about $311 a month, which is the figure that goes in the vehicle finance slot.
Expected ramp months is a judgment, not a fact. Make it explicit and write down what would tell you it was wrong. If the phone is quieter than assumed by the end of month two, you want that as a variance from a written expectation rather than as a feeling.
The temptation is to set ramp months low because the plan looks better. Set the number you would defend to a lender, then ask whether the funding still works.
At a $4,000 monthly burden, three ramp months need $12,000 and six need $24,000.
Stock costs more than the opening buy
Stock costs more than the opening buy
| Stock class | Opening buy | What drives repeat cost | Failure if underbought |
|---|---|---|---|
| Key blanks | Widest range you will meet | Job mix, keyway spread in the area | Return visit for a blank you should carry |
| Pin kits and springs | Full depth in the systems you service | Rekey volume, master keying work | Job stops halfway |
| Cylinders and cores | Common functions and finishes only | Replacement versus rekey ratio | Customer waits, or takes a wrong finish |
| Door hardware | Narrow, matched to local stock | Commercial work, damage jobs | Second visit, second travel cost |
| Electronic parts | Only if access control is in scope | Project work, not call-outs | Ties up cash between projects |
| Transponder keys and remotes | The two or three vehicle families you meet most | Vehicle mix, keyless entry demand | A customer who calls someone else |
Most underbuying shows up as a second visit. Cost per unrecovered return trip = travel time x loaded hourly cost + vehicle running cost for the distance. Multiply by how often it happens and compare against the cost of carrying the item. That comparison should decide the opening list, not a general instinct toward lean stock.
At a loaded cost of $45 to $70 an hour, a 30 minute return plus 12 miles of driving prices one trip at roughly $40 to $70. Ten of those in a year cost more than the blanks you chose not to carry.
Stock Classes: Opening vs Repeat Cost
Stock class
- Key blanks
- Widest range you will meet
- Pin kits and springs
- Full depth in serviced systems
- Cylinders and cores
- Common functions and finishes
- Door hardware
- Narrow, matched to local stock
- Electronic parts
- Only if access control in scope
Opening buy
- Key blanks
- Job mix, keyway spread
- Pin kits and springs
- Rekey volume, master keying
- Cylinders and cores
- Replacement versus rekey ratio
- Door hardware
- Commercial work, damage jobs
- Electronic parts
- Project work, not call-outs
What drives repeat cost
- Key blanks
- Return visit for missing blank
- Pin kits and springs
- Job stops halfway
- Cylinders and cores
- Customer waits or wrong finish
- Door hardware
- Second visit, second travel cost
- Electronic parts
- Ties up cash between projects
Failure if underbought
- Key blanks
- Pin kits and springs
- Cylinders and cores
- Door hardware
- Electronic parts
Matching funding to asset life
Consumables and stock come from cash or a short revolving facility, because they turn over. Tooling has a long life and can sit on term finance. A vehicle should be financed over a term no longer than you intend to keep it, or you are still paying for a van you have replaced.
Matching Funding to Asset Life
Asset type
- Consumables and stock
- Cash or short revolving facility
- Tooling
- Term finance
- Vehicle
- Finance term
Funding source
- Consumables and stock
- Because they turn over
- Tooling
- Long life
- Vehicle
- No longer than you intend to keep it
Term guidance
- Consumables and stock
- Tooling
- Vehicle
Compare sources on their written terms rather than their marketing:
Matching funding to asset life
- your own savings
- a term loan from a bank or credit union, typically $5,000 to $50,000 for an owner with filed returns
- equipment finance from the supplier, typically 7% to 15% APR over 2 to 5 years
- an SBA-backed loana Microloan up to $50,000 through a nonprofit intermediary, 7(a) up to $5 million, or 504 for fixed assets
- a family arrangement documented like any other loan
Kiva US raises up to $15,000 at 0% interest through crowdfunding, and Accion Opportunity Fund lends to owners with thin credit files.
SCORE and your regional Small Business Development Center advise for free. Business credit cards often carry 0% on purchases for 12 to 18 months before the rate climbs above 20%.
The Small Business Administration business guide describes the funding routes and what each expects from an applicant. The IRS starting a business material covers how the structure you choose affects the tax treatment of what you borrow and buy.
Whatever you take, write the repayment into the monthly fixed burden before you set the rate.
The financial section carrying this arithmetic is described in the locksmith business plan. The phase where the funding conversation happens is in the startup sequence for a locksmith business.
Costs people forget
Permission costs recur. Registrations and licenses renew, and the cycle is not always annual, so put every expiry in a calendar. Confirm the cycle with your state licensing board and your city clerk, and the locksmith licensing and compliance guide covers how to record those answers.
Training costs recur too and are usually the first line cut. If a second technician is planned, the training time is a real cost against a real person, which the locksmith hiring and training guide treats in detail. The service mix behind all of this is decided in the locksmith startup and market guide.
Payment processing hides in plain sight. Square charges 2.6% plus 10 cents on a swiped card, and Stripe charges 2.9% plus 30 cents online. On $6,000 of monthly card takings those rates cost roughly $160 to $190.
Quotes that do not convert are a cost too. Neither the processing fees nor the quoting time belong in the opening buy; both belong in the fixed burden.
Public claims made while raising money are still claims, and the FTC advertising standards apply to what you publish about the business.
Common questions
What is the single largest startup cost?
For most mobile shops the vehicle, then tooling. A used cargo van typically runs $12,000 to $25,000, and a new one $38,000 to $55,000.
For an automotive-focused shop, programming equipment and its subscriptions can overtake the vehicle, at $1,500 to $5,000 in the first year. Decide the mix first and let the cost ranking fall out of it.
Can I start with used equipment?
Often, and for some tooling it is the sensible route. The judgment is serviceability and calibration rather than age.
Ask what wear looks like on that machine, whether cutters and jaws are still available, and whether the seller can show it cutting accurately before money moves. A used Ilco or Rytan duplicator at $150 to $400 is common, and replacement cutters typically run $25 to $80 each.
How much working capital is enough?
Enough to cover the fixed burden for the months you honestly expect the ramp to take, plus a margin for the month you did not expect.
Write it as a formula with your own inputs, so a long ramp shows you exactly what has to change. At a $4,000 monthly burden, three months is $12,000 and six months is $24,000.